Last year, Etrade had alerts all over its interface and sent me notices that I may receive updated tax info, after I received my original 1099 form. I was grateful since I knew to wait to file my taxes or risk needing to refile.
This year, there were no alerts and no messages.
I assumed Etrade had updated its business processes from last year to catch up with changing regulations and was prepared to get accurate tax information to me on time.
I even read blog posts that other brokerages were warning their customers that they may get amended 1099 statements. I was pleased that Etrade was more on the ball than these other brokerages.
Boy was I wrong.
Etrade backtracked big time. On Saturday, March 1st , I got an amended 1099. I got an amended tax form in March.
As I wrote before, I don't mind that with ridiculously complicated regulations, amended forms are necessary. I'm disappointed in my government that we have overly complicated regulations in how real estate investments are taxed, but vastly inadequate regulations in how those investments are made.
Anyway- Etrade could have put the same message up that it did last year but they did not. They could have emailed me as a customer with real estate investments and foriegn investments that I may receive an amended tax form but they did not.
The good news is that I have not filed my taxes yet and I was able to sign into my turbotax account and re-download my statement from Etrade and see the information and all the impacts automatically updated. What I owe in state taxes went up almost 100%. Fortunately the increase in my federal refund went up more than enough to cover the difference.
Shame on you Etrade for not communicating what you communicated last year. You even included a document with the amended statement with a form dated 1/08 called "Enclosed is your amended Consolidated Form 1099." If you knew in 1/08 that you needed a form for your customers, why not let us know?
Shame on me for assuming Etrade was on the ball.
Kudos to me (maybe my unconscious) for waiting to file my taxes even though I had already done them.
3.02.2008

2.28.2008
Correction- JPMorgan Rate 1.69%
I wish I had taken a screenshot of the rate I was looking at when I wrote this post so I can see what I did wrong! I must have been posting much too hastily.
The JPMorgan Municipal Money Market Fund offered in Etrade's Brokerage account currently yields 1.69% This is less than 2.70% it was yielding in December, but much more than the 0.64% I posted yesterday. I did start that post a day or two before I published it but I can't imagine rates changed that much in two days.
My apologies!

Thanks to David for commenting and helping me realize I was wrong. To further clarify: the California Fund Yields 1.56%. This is equivalent to 2.65% if you pay the highest possible Federal and State taxes as a CA resident: "Based upon the highest combined federal and California individual income tax rate of 44.3%."
David asks how to keep up with the best account a bank is offering. First of all, when you do your taxes, calculate your actual tax rate. That will help you get a sense of how much more than 1.56% you are keeping by using a CA specific money market fund as a resident of CA.
Both the bank rate and money market rate have dropped as well as rate at most every bank out there, so the goal is not to find an that is not dropping (if that is your goal, CDs might help, but you'll miss out when rates go up if you are tied up in a CD). Banks (like Etrade) play games with their competition, keeping rates higher a little longer, trying to woo customers over, only to then drop the rate, maybe more than the competition.
If you really want to keep on top of the best bank offers out there, I recommend checking out the Bank Deals weekly summary. If you have an Etrade Brokerage then opening the Etrade Savings account may make sense so that you can keep your cash in either the Brokerage or the Savings account, whichever is better for you at the time based on rates and your taxes. I'm glad I opened the savings account since it can take a while to transfer money to and from the Brokerage account from a non-Etrade bank.
That said- don't close your old bank until your new one is doing everything your old one did.
I am still waiting on an ATM card for the Etrade Checking account I opened in December.
Let that serve as an example of the quality of service you might encounter using discount online services versus a local branch. So assess your tolerance for hassle before making too many changes.
2.27.2008
Falling Interest Rates- Savings vs Money Market at Etrade
Bank Deals has an update about Etrade Bank rates. The author also notes that Etrade has extended its $25 sign up bonus.
I opened a complete savings account at the end of last year and they did not credit my account $25 within 30 days as promised.
Once I pointed this out, they credited me the next day.
Bank Deals does not cover money market funds in brokerage accounts, but it is interesting to note that Etrade's Brokerage offers "JPMorgan Municipal Money Market Fund" which is tax free. It currently returns 0.64%. It was returning 2.70% as recently as 12/30/07.
I had much of my savings in my brokerage as it gave me over 3% after taxes which was better than my Citibank Savings account. Then I jumped on Etrade's 5% +$25 offer! Well the 5% rate may not have lasted but I am still earning more than what Citibank was paying me in December.
And I'm glad I moved my cash out of my brokerage. Less than 1% interest is terrible.
2.25.2008
Turbotax Discount 25% Off Available for Anyone
Looking around for discounts off TurboTax, I found one offered by Fidelity. The nice thing is you do not have to be a Fidelity customer to take advantage!
If you are interested, click here.
And then choose the "Visitor Entry" link.
There may be better deals out there but this is the best I found so far.

But- if you file a 1040EZ- be CAREFUL!!!! You can use TurboTax for free at this link.
If you go direct to TurboTax the 1040EZ is free:

But if you want the 25% discount, the 1040EZ costs $14.95:

I understand that 25% off free is difficult to calculate, but come on. Charging $15 to give a discount off something that you give away for free????
That's just wrong.
2.24.2008
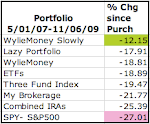
Portfolio Update 2/22/08: Another Positive Week But Still in the Red
Despite a second week in a row of gains, all the portfolios remain in the red since last May.

My Brokerage and IRA had the best week, returning over 7/10 of 1%. Despite the worst weekly performance of the bunch, The WylieMoney 20 Mostly Managed portfolio remains firmly in the lead.


My Brokerage and IRA had the best week, returning over 7/10 of 1%. Despite the worst weekly performance of the bunch, The WylieMoney 20 Mostly Managed portfolio remains firmly in the lead.

WylieMoney 20 Mostly Managed
 WylieMoney Slowly
 Lazy 20 Mostly Index
 Three Fund Index
 ETF 20
 S&P 500

 WylieMoney Slowly
 Lazy 20 Mostly Index
 Three Fund Index
 ETF 20
 S&P 500

2.18.2008
Portfolio Update 2/15/08: Will ETFs Come Back?
All the portfolios managed a gain for the week and all but one managed a gain on Friday. The S&P 500 portfolio was down ever so slightly, but a little diversity in your mix and even Friday was a good day.
 I updated the IRA I track to include all my IRAs and as a result "My IRA" has tumbled to the bottom of the pack. I am not surprised to see it sitting between SPY and the ETF portfolio since my IRA is almost 15% invested in SPY and largely made up of additional ETFs.
 SPY had the best week last week and the ETF portfolio is beating all the Vanguard portfolios YTD!
That said the hand picked mostly managed WylieMoney portfolios remain in the lead and my brokerage sits up near the top because in that account at least, I eat some of my own soup.
WylieMoney 20 Mostly Managed

WylieMoney Slowly

Lazy 20 Mostly Index

Three Fund Index

ETF 20

S&P 500- SPY


WylieMoney Slowly

Lazy 20 Mostly Index

Three Fund Index

ETF 20

S&P 500- SPY

2.17.2008
I Can't Wait for my Apology Check!
I find it ironic that a Republican administration's response to too little regulation/oversite over loan company lending practices is to take tax money, overwhelmingly paid by high income earners, as they like to remind me, and give some of that money to me.
I think of it as less of a stimulus and more of an "Oops sorry. This should make you feel better."
It may very well be that reduced regulation and high enough tax revenue (thus the irony at the Republicans doing this) to send out the occasional 'apology check' when unregulated business schemes collapse IS the most efficient way for the economy to chug along...
But does that make it the best choice for a Democratic/free market society?
Actually the apology checks are the least interesting regulation getting rushed through the door these days. (Interesting pattern of 'spin a situation as a crisis so government has to rush changes into law.')
Businesses are getting nice perks out of this. Businesses that have nothing to do with sub-prime lending (no WMDs) or are in no way associated with mortgage debt (did not associate with Osama) need these changes passed NOW as a response to this economic CRISIS.
And wealthy home owners will be able to refinance large mortgages at lower rates, generally saving far more than $600. Actually, I wonder how much top tax payers will be able to save after refinancing their loans and how that compares to how much tax they had to pay to give the rest of us apology checks...
Those losing their jobs as a result of the recent turmoil and those struggling with payments for things like heating oil, will have to be content with their $600.
"Republicans yesterday blocked consideration of the stimulus measure approved by the Senate Finance Committee because they opposed Democrats' plans to add extended unemployment benefits, home heating assistance and alternative energy tax credits to the measure passed by the House."
Anyway, I assume that a scientific assessment of the loan changes and business perks proved that they would offer far more financial stimulus than extended unemployment benefits and home heating assistance and that is why that decision was made... so much research and assessment has gone into the other hasty government action taken in similar 'spin crisis, act now' campaigns and that have worked out well (WMDs, war planning, post war planning, etc.) so I feel good about things this time too.
Subscribe to:
Posts (Atom)